
The former ECB chief drops a political bombshell in Strasbourg: without a unified government, Europe will remain a second-tier power.
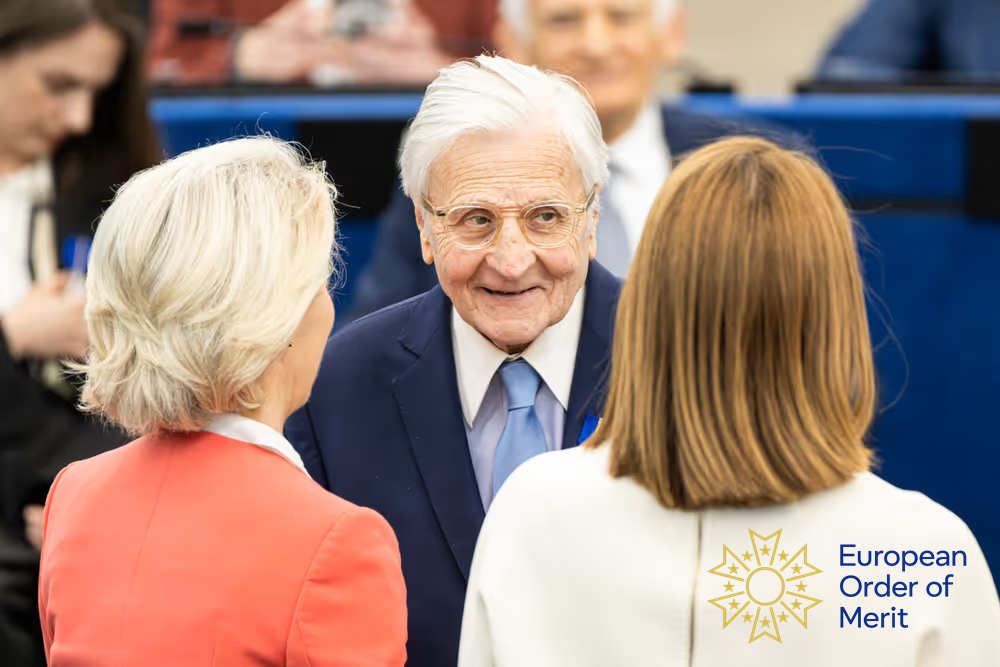
At 83 years old, Jean-Claude Trichet measures political progress in centuries. He has earned that right. As the man who spearheaded the European Central Bank for eight turbulent years, he successfully steered the euro through its most existential crisis. He knows firsthand the devastating price of political shortsightedness. On Tuesday 19 May, while accepting the European Order of Merit at the European Parliament in Strasbourg, Trichet didn’t mince words about his core conviction: “We need a federal European Union.”
Speaking with a small group of journalists immediately following the ceremony, Trichet delivered an analysis every bit as sharp and clear as Mario Draghi’s recent warnings. His thesis is simple: without a unified military and a single foreign policy, Europeans will remain exactly what they are today: potential vassals. They risk becoming economic dependents of the United States, or worse, “the new vassals of Russia, which would be the ultimate disaster.”
You don’t have to look far for proof. Take the ongoing trade negotiations with Washington. Trichet labels Europe’s handling of the situation “an absolute disgrace.” The reason? Donald Trump leverages the full, unified weight of the United States, while European leaders scramble to protect their own narrow interests in a game of every man for himself.
The Euro Was Just the Beginning
Can a true political union ever materialize when EU member states are constantly fighting over a geographically fair return on every single euro spent from the European budget? Trichet knows better than anyone that the euro is currently Europe’s only truly federal powerhouse.
Yet, looking back, the currency itself was a hard-fought battle. Germany was notoriously reluctant to abandon the Deutsche Mark, fearing it would dilute their monetary strength. At the time, Chancellor Helmut Kohl demanded a “political union” as a mandatory prerequisite for the euro. “It was obviously an excuse to delay the launch,” Trichet admits. “But he wasn’t wrong, either.”
Fast forward 27 years. The eurozone has expanded to 21 members, yet Trichet is deeply frustrated by how little has changed on the ground. “We still don’t have a single market for commercial banking, capital markets, telecommunications, or major tech platforms,” he laments. “In fact, we don’t even have any major digital platforms.” Instead, Europe remains crippled by vertical silos that serve as highly inefficient economic barriers.
This fragmentation is on full display in the corporate world. “Country X doesn’t want its top bank bought out by a rival from Country Y. We see it every single day,” Trichet points out. He is referring to the recent corporate showdown where the Italian bank Unicredit tried to take over Germany’s Commerzbank, only to run straight into a political brick wall erected by Berlin. The former ECB chief calls this a “glass ceiling” that actively suffocates European power on the global stage.
Airbus: The Exception That Proves the Rule
When asked to name Europe’s single greatest federal industrial success story, Trichet doesn’t hesitate for a second. “There is only one: Airbus (where Trichet served as a board member for five years). It’s the world leader in civil aviation. But there isn’t a second one. Why? Because we don’t have a true single market.”
Both the Draghi and Letta reports laid bare the staggering economic toll Europe pays for its national fragmentation. The continent continues to safeguard countless technical barriers across various industries, all to protect local monopolies and regional champions. The result? Lacking access to a frictionless domestic market, these companies remain economic dwarfs in global competition.
The Fear Factor and the American Solution
The political roadblock is predictable: smaller European nations are terrified of being swallowed whole by powerhouse neighbors like France or Germany. It is a structural hurdle Trichet recognizes well.
“That is the fundamental challenge of any federation,” Trichet notes. “The United States solved this problem with the Senate, where every state, large or small, gets exactly two senators. Is it perfectly democratic? Not at all. But that is how you successfully build a federation with the consent of all its moving parts.”
For Europe, the path to a political union will have to start with national defense. A unified military demands a unified foreign policy. And a unified foreign policy is completely useless unless European nations can agree on shared geostrategic analyses. That realization is slowly starting to sink in. The return of large-scale warfare to European soil has fundamentally changed the math. European leaders are beginning to understand that if they stay the course, they risk becoming vassals to foreign powers that are already organized and on the offensive.
The Missing Finance Minister
During his acceptance speech, Trichet reminded the audience that back in 2011, he proposed creating a dedicated eurozone finance minister. He also advocated for the European Parliament to have the ultimate tie-breaking vote whenever a member state clashed with EU institutions like the Commission or the Council. Trichet envisioned this crisis-mode surge in centralized executive and legislative power as a “federation by exception.”
Fifteen years later, that vision is dead in the water. The eurozone finance minister idea, once championed and later abandoned by French President Emmanuel Macron, never materialized. Worse, the Council, which represents national governments, increasingly views the European Parliament as a slow, unpredictable body packed with populist factions openly hostile to the EU. The odds of member states ceding the final word to Parliament are practically zero.
France’s Financial Drift
This half-baked federalism hits individual nations right in the wallet, and France is currently paying a steep price. Trichet knows the data by heart. In 2008, when Lehman Brothers collapsed, the French public debt-to-GDP ratio was at 64%, mirroring Germany’s fiscal health exactly.
“We weren’t targeted by the markets like Greece, Ireland, Portugal, Spain, or Italy because our fiscal standing was credible,” Trichet emphasizes. But since then, France has completely lost its grip. “Regardless of the economic circumstances or who was in office, we let things slide.”
Today, France sits as the third most indebted country in the eurozone, outpaced only by Italy and Greece. “It is well past time for France to clean up its public finances,” Trichet warns. “This is the ultimate French vulnerability.”
While he gives credit to the Macron administration for doing solid microeconomic work, boosting domestic business creation and pulling in foreign direct investment, he argues the big picture was ignored. “We completely neglected public finances. That needs to be the nation’s absolute top priority.”
Top political figures have tried to warn the French public about the looming financial crunch, but the message isn’t sticking. The public hears the warnings, but nobody wants to take the hit. “It’s a uniquely French malady,” the former central banker says with a note of disillusionment. “France has gotten comfortable asking the rest of the world to bankroll its excess spending. Everyone has grown addicted to easy money.”
The Greek Example vs. Italy’s Crisis
If Europe wants a real lesson in the dangers of fiscal negligence, it should look to Greece. Once an economic pariah, the country is transforming into a model of fiscal discipline. Trichet remembers the darkest days of the eurozone crisis vividly, when global markets were betting heavily on a “Grexit” and powerful European governments, most notably Germany, were actively trying to push Athens out the door.
But Greece chose a different path. The Greek people refused to abandon the euro, and successive governments held the line through monumental sacrifices, tackling massive double-digit deficits in both public spending and current accounts. “The Greek people and their leaders deserve immense credit,” Trichet says.
The turnaround is striking. According to official financial projections, Italy is on track to overtake Greece as the most indebted nation in the eurozone, with the Italian Treasury projecting a debt-to-GDP ratio of 138.6%. Meanwhile, Greece expects to slash its ratio to roughly 137% this year, down from 145.9% last year. It is a massive recovery for a country whose debt peaked at a staggering 209.4% in 2020.
For Trichet, the takeaway is simple. “Nothing is ever truly finished.” Not for Greece, not for France, and certainly not for Europe. The only question left is whether today’s leaders can summon the political courage to act, an asset that remains in critically short supply.